Articles
Investing written the way we would explain it across a table: what the number means, why it moves, and what an owner should do about it. Every article links down to the company pages and the X-Ray reports that carry the evidence.
Broadcom or Nvidia: two ways to sell the same boom
Both are extraordinary businesses riding the same wave. They are not, however, the same investment — and the thing that separates them is a number you can count on one hand.
Companies in Focus
Opinion, with the evidence attached: what is actually happening inside a business people are arguing about.
Is Costco overvalued? It has been for thirty years
Charlie Munger called the price the trouble with Costco and never sold a share. Both halves of that sentence are instructive, and most people only quote one.
Is JPMorgan still a fortress? The record quarter, taken apart
A bank is the one business where the balance sheet is the product. JPMorgan's just produced a record — and its own chairman told you why it will not repeat.
The patent cliff: how to price a loss you can see coming
A patent expiry is the rarest thing in investing: a large, certain loss with a date attached. Which is exactly why the market gets it wrong in both directions.
Is Nvidia's growth sustainable? One line in the accounts is trying to tell you
Nvidia earned in six months what it took the whole of last year to earn. That is not the interesting part. The interesting part grew faster than revenue did.
SpaceX is public. Its first 10-Q is not about rockets.
The SEC does not classify SpaceX as an aerospace company. It classifies it under data processing — and the first set of public accounts explains why.
Nike: what is actually going on?
The share price has halved and the explanations are all vibes: brand fatigue, On and Hoka, China. The accounts say something more specific, and it was hiding inside a headline everyone read as good news.
Can Adobe beat AI? The question already changed
The bear case used to be that AI makes Photoshop unnecessary. The September numbers retired that argument and replaced it with a duller, more dangerous one.
How do you run a business designed to shrink?
Every business school teaches growth. Almost none teach the harder discipline: how to run something profitable that will be smaller every year for the rest of its life.
Dividends & Income
Yield, safety, growth — and how to tell a durable payout from a trap.
6% now or 2% growing: which one actually pays you more
Everyone says growth beats yield. The arithmetic agrees, and then adds a detail nobody mentions: it takes two decades, and most people are not investing for two decades.
The ex-dividend date, and why buying the day before doesn't work
Everyone learns the rule: own it before the ex-date and the dividend is yours. Almost nobody is told what the market does to the share price that same morning.
Monthly dividend stocks: what you gain, and what you pay for it
Twelve cheques a year instead of four is a genuine convenience. It is not a genuine edge — and the screen that starts with 'monthly' is selecting for something other than quality.
Why a REIT's payout ratio looks impossible
A payout ratio above 100% would be a red alert at any normal company. At a REIT it is the default, and the reason is an accounting entry that costs nobody a cent.
How to tell if a dividend is safe
A high yield is not a reward for patience — it is usually the market's way of saying it does not believe the payout. Here is how to check, in the order that matters.
Valuation
What a business is worth, and what you are being asked to pay for it.
How much growth is already priced in?
People argue about whether a stock is expensive. The more useful question has an answer: what would have to be true for today's price to be right?
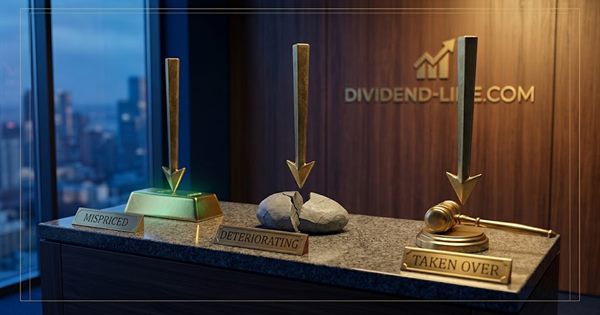
Three ways a stock falls 60%, and only one of them is a bargain
The question people ask is 'why is it down?'. The question that pays is 'which of the three kinds of down is it?' — because two of them are traps and they look identical from the outside.
Moats & Business Quality
Why some businesses keep their profits and others give them away.
Pricing power: the only part of a moat you can actually measure
Everyone claims a durable advantage. Inflation is the audit: it asks every company the same question at the same time, and the gross margin publishes the answer.
We scored 71 moats. Only three got full marks.
Everyone can define a moat. Far fewer can tell you which companies have one, which is why it is worth counting rather than theorising.
Portfolio & Temperament
Position sizing, holding periods, and the behaviour that decides returns.
How many stocks should you own?
The maths of diversification has a very clear answer, and almost nobody's portfolio reflects it — in either direction.
Why trading doesn't pay
Most arguments against trading are about psychology. The stronger argument is arithmetic, it is not close, and you can work it out on the back of an envelope.
Markets & Macro
Rates, cycles and sentiment — read as an owner, not a trader.
What 71 company reports say about this market
Forget whether the market is expensive. Our own scores say something more actionable: the gap between two companies in the same sector is twice the gap between sectors.
What is actually taking the return out of REITs
Property is supposed to be the simple part of a portfolio: buy buildings, collect rent, get paid. Three things sit between the rent and your return, and only one of them is in the news.