We have published 73 deep company reports. Eight of them scored 8 out of 10 or better.
That is 11%. The average score across all 73 is 6.72, and 21% scored below 6. Four carry a verdict of "too hard", which means we read everything and declined to form one.
A research house asking whether its own work is worth doing is an awkward article to write. We think the honest answer is useful enough to publish anyway.
What 73 careful looks actually produced
| Score | Companies | Share |
|---|---|---|
| 8.0 and above | 8 | 11% |
| 7.0 – 7.9 | 27 | 37% |
| 6.0 – 6.9 | 23 | 32% |
| Below 6.0 | 15 | 21% |
| of which: "too hard" | 4 | 5% |
Two readings of that table, and both are true.
The discouraging one: we did a great deal of work to find eight companies. Each of those reports takes days. If that is the hit rate for people doing this full time, the case for an ordinary investor picking shares casually is weak.
The encouraging one: the eight were findable, and nothing about them was secret. They are large, famous companies whose filings anybody can read. The work was not insight — it was reading.
Twenty-one per cent of the companies we examined scored below 6. Every one of them looked perfectly respectable from the outside, which is the entire reason the work exists.
Where the money is actually going
Our report on T. Rowe Price found something the firm's own press release did not lead with. Assets reached a record $1.89 trillion — and of the $183.7 billion by which they grew in the quarter, markets supplied $190.2 billion and clients withdrew $6.5 billion.
Every dollar of the record came from prices rising. The business itself lost money to the exit.
And the withdrawals were not spread evenly. They were concentrated entirely in fundamental active equity — which happens to be 48.6% of everything the firm manages. Management guided the second half to be "meaningfully more challenging".
That is a structural movement, not a bad quarter, and it is the clearest available evidence of what investors as a group have concluded.
What we actually think you should do
- Most of your money belongs in an index. Specifically, the money that must simply compound without depending on your attention, your mood, or whether this year is busy. That is most people's money, and it is not a defeat — it is a correct allocation of effort.
- Pick shares with the part you will genuinely work on. Not a share of your wealth chosen by formula — a share chosen by how much reading you will actually do. If that is three companies, own three.
- The worst outcome is thirty names picked casually. It carries every cost of active investing and produces the result of an index, minus the trading. This is the most common portfolio we are asked about.
- If you will not read a 10-K, do not pick shares. That is the whole edge available to an individual. There is no substitute and no shortcut, and the twenty-one per cent that scored below 6 are the evidence.
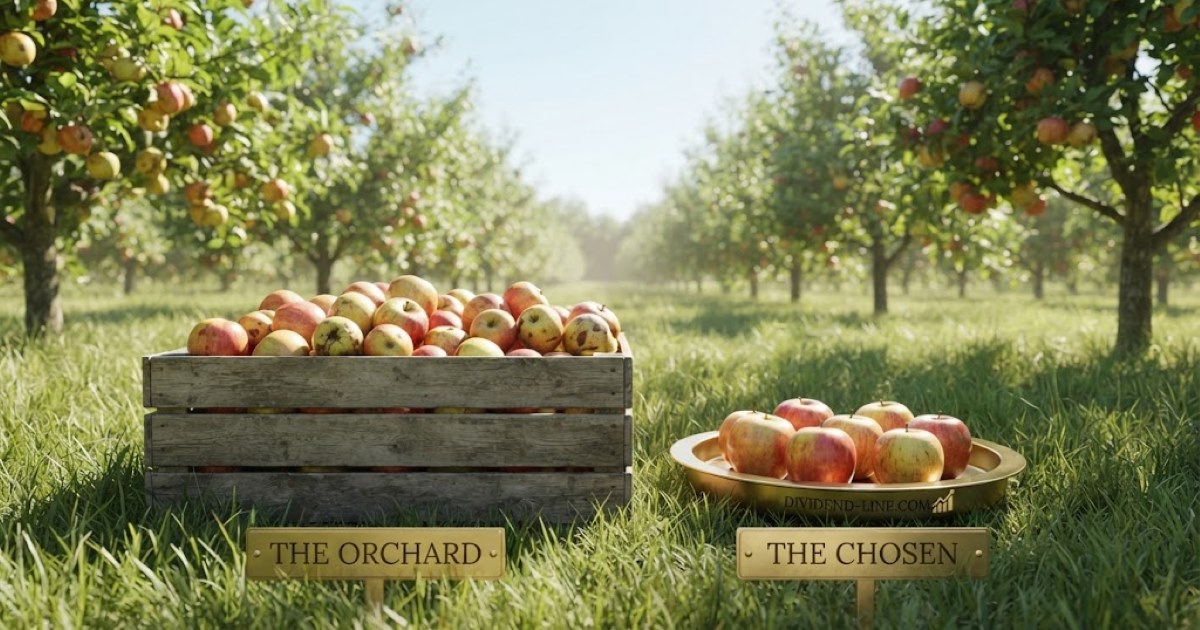
An index buys the orchard. Every tree, including the ones that will not make it — and historically that has worked very well, because the good ones more than carry the rest.
What it cannot do is decline. It holds Tesla at 4.2 and Oracle at 5.2 in the same proportion as the eight at 8.0 and above, because it is not allowed an opinion.
For an investor who will do the reading, that is the opening. Not beating the market by cleverness — simply not owning the things you have read about and did not like. It is a smaller claim than the industry usually makes, and we think it is the true one.
Three questions, answered honestly
Not articles — annual reports. If the answer is none, the index is not a compromise for you, it is the correct answer, and acting on it will improve your results immediately.
Following means reading each quarter and knowing what would change your mind. Most people with full-time jobs can do five to ten. Size the picked portion of your portfolio to that number, not the other way round.
If the honest answer is "to beat the index", the odds in our own table are sobering. If it is "to own a small number of businesses I understand and avoid the ones I do not", that is achievable and the evidence supports it.
We will keep publishing the reports, including the ones that conclude "too hard" and the twenty-one per cent that score below 6. Those are the useful ones — a research library is worth more for what it tells you not to own than for what it recommends, and that is the part an index cannot do for you.
A record it did not earn, in the part of the industry the money is leaving.
The flow decomposition and the active-to-passive shift, worked through.
Frequently asked
Should most people just buy an index fund?
For most of their money, yes — and we say that as people who write company research for a living. Of the 73 companies we have examined in depth, eight scored 8 out of 10 or better. If a full report is needed to find roughly one in nine, then picking shares is worth doing only with money you will genuinely apply that effort to, and the rest belongs somewhere it does not depend on your attention.
Is stock picking worth the effort?
It depends entirely on whether you will do the work, repeatedly, for years. The eight best businesses in our library were findable — nothing about them was secret. But they were found by reading filings, and the twenty-one per cent that scored below 6 looked perfectly respectable from the outside. The effort is the whole edge; without it the activity is worse than an index, not better.
Why are investors leaving active funds?
Because of cost and consistency, and the numbers are stark. T. Rowe Price reported a record $1.89 trillion under management while clients withdrew $6.5 billion — markets supplied every dollar of the record. The withdrawals were concentrated entirely in fundamental active equity, which is 48.6% of what the firm manages.
Can you do both?
That is what we would suggest, and it is what the arithmetic supports. An index holding for the money that must simply compound, and a smaller number of individual positions for companies you have actually examined and will keep examining. The failure mode is a portfolio of thirty names picked casually, which carries the costs of active investing and the results of an index.